European leveraged loans have become an integral part of many institutional portfolios. The asset class has established a solid position in the liquid high-yield credit market and stands out thanks to its unique characteristics and diversification benefits. The loan market has endured remarkably well through the past years' market volatility and events, with lower volatility and sensitivity to rates. While yielding over 7% today and remaining an attractive component of a diversified credit portfolio, the market is more demanding today, as in EUR HY overall, where asset dispersion between high entry yields and high-quality assets with tight spreads underscore the importance of careful credit selection and prudent capital allocation.
Resilience through a volatile cycle
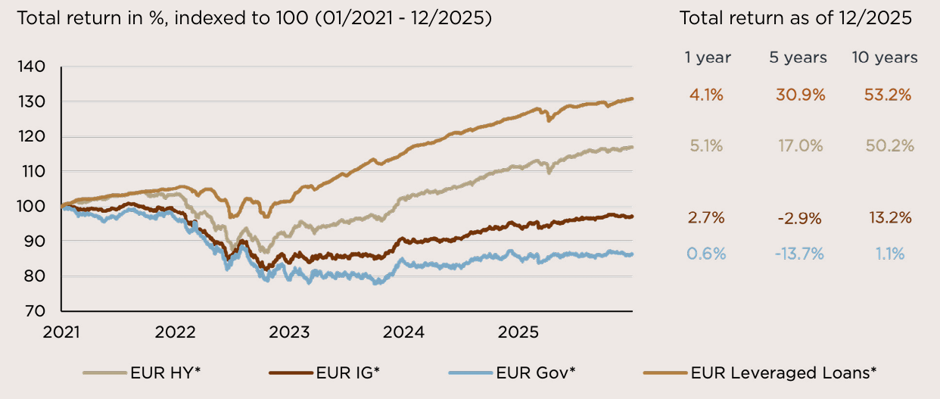
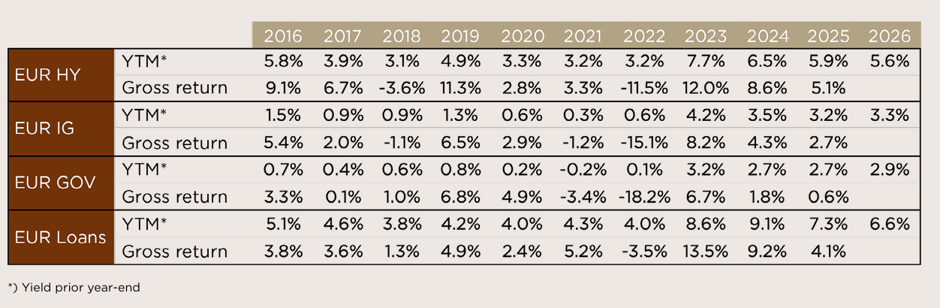
Looking back, whilst the asset class was not immune to the interest rate shock and the war in Ukraine in 2022/23, it demonstrated clear relative resilience in 2022 partly due to its floating rate nature – followed by strong returns in 2023/2024 that outperformed those of high-yield bonds (see figure).
Gross returns on European leveraged loans compared with European high-yield (HY) bonds, investment-grade (IG) bonds and government bonds (GOV)
Source: ICE BofA bond indices, Morningstar European Leveraged Loan Index “ELLI”. Source: Bloomberg, PitchBook Data Inc, ICE BofA.
Distinguishing opportunities in distress situations
Current yields remain attractive by historical standards, but spreads have tightened to the lower end of the range, whilst the gap between stronger and weaker issuers has widened. This bifurcation is driven by investor sensitivity towards issuer performance, capital structure, ratings, maturities, refinancing capacity, enterprise valuations, exit possibilities, and sponsor positioning. Material issues can lead to a meaningful deterioration in prices, weaker liquidity and steeper repricing in the secondary market. At the same time, the imbalance between ample demand and limited new deal supply persists, one that reaccelerated buyout activity would help to ease and improve managers’ credit selection universe.
Weaker companies may appear attractive with double-digit entry yields, but credit picking makes all the difference. Some situations are ultimately heading towards restructuring and pose a higher risk of actual credit losses, while others offer a path to recovery offering outstanding returns for patient long-term investors (for example, in a CCC category, which accounts for c. 6 per cent of the market today, the odds are almost 50/50). Be it a new investment or existing exposure, what matters, therefore, is a prudent and comprehensive credit analysis, manager’s actions and flexibility. As the secondary market is reacting increasingly quickly and sharply to negative signals, investors face a two-tiered environment: at the upper end of the quality spectrum, discipline is required, as good companies are not automatically good investments if the price is too high and the spread too low. At the lower end, opportunities arise, but only where the market overestimates actual risks rather than pricing them in correctly.
Traditional default rates have remained very low to date (c. 1 per cent on average for 2024–2026, according to LCD PitchBook), while broader credit event indicators have been c. 2 per cent since 2025; however, even these remain moderate.
Higher rates, in turn, are not fundamentally negative for leveraged loans, which are floating rate instruments, and hence moderately higher Euribor rates support coupon carry and returns for investors. If significantly higher rates coincided with weaker growth, weaker operating margins, cash flow and liquidity, conditions would become more stressed, as we saw in 2022/23. However, even those adverse conditions ultimately proved to be temporary and less disruptive.
Further information:
Mandatum Leveraged Finance, January 2026
Mandatum Leveraged Finance, September 2024
Blogpost by Kimmo Salokoski, Senior Portfolio Manager
This article is for marketing and informational purposes only and does not constitute investment advice or a solicitation to invest or to participate in any trading, investment strategy or an offer to buy or sell any security or financial instrument. The presented information is based on the information available at the time the article was created as well as on the views and estimates of Mandatum Asset Management Ltd (“Mandatum”) at that time. The information may change without notice. The investments discussed on this article may not be suitable for all investors. Investors should make their own investment decisions based on their financial objectives and financial resources and should seek advice from their investment, legal and tax advisers.
Investment involves risk. The value of investments and the income from them can go down as well as up and you may not get back the amount originally invested. Past performance does not guarantee future returns. If an investment is denominated in a currency other than your base currency, changes in the rate of exchange may have an adverse effect on value, price or income. Mandatum does not guarantee the accuracy or completeness of the information and does not accept liability for any loss arising from its use.
THE MORNINGSTAR ENTITIES DO NOT GUARANTEE THE ACCURACY AND/OR THE COMPLETE NESS OF THE MORNINGSTAR EUROPEAN LEVERAGED LOAN INDEX OR ANY DATA INCLUDED THEREIN AND MORNINGSTAR ENTITIES SHALL HAVE NO LIABILITY FOR ANY ERRORS, OMISSIONS OR INTERRUPTIONS THEREIN.
SOURCE ICE DATA INDICES, LLC (“ICE DATA”), IS USED WITH PERMISSION. ICE® IS A REGISTERED TRADEMARK OF ICE DATA OR ITS AFFILIATES, AND BOFA® IS A REGISTERED TRADEMARK OF BANK OF AMERICA CORPORATION LICENSED BY BANK OF AMERICA CORPORATION AND ITS AFFILIATES (“BOFA”) AND MAY NOT BE USED WITHOUT BOFA’S PRIOR WRITTEN APPROVAL. ICE DATA, ITS AFFILIATES AND THEIR RESPECTIVE THIRD PARTY SUPPLIERS DISCLAIM ANY AND ALL WARRANTIES AND REPRESENTATIONS, EXPRESS AND/OR IMPLIED, INCLUDING ANY WAR RANTIES OF MERCHANTABILITY OR FITNESS FOR A PARTICULAR PURPOSE OR USE, INCLUDING THE INDICES, INDEX DATA AND ANY DATA INCLUDED IN, RELATED TO, OR DERIVED THEREFROM. NEITHER V.6 071320 ICE DATA, ITS AFFILIATES NOR THEIR RESPECTIVE THIRD PARTY SUPPLIERS SHALL BE SUBJECT TO ANY DAMAGES OR LIABILITY WITH RESPECT TO THE ADEQUACY, AC CURACY, TIMELINESS OR COMPLETENESS OF THE INDICES OR THE INDEX DATA OR ANY COM PONENT THEREOF, AND THE INDICES AND INDEX DATA AND ALL COMPONENTS THEREOF ARE PROVIDED ON AN “AS IS” BASIS AND YOUR USE IS AT YOUR OWN RISK. ICE DATA, ITS AFFILIATES AND THEIR RESPECTIVE THIRD PARTY SUPPLIERS DO NOT SPONSOR, ENDORSE, OR RECOM MEND MANDATUM, OR ANY OF ITS PRODUCTS OR SERVICES